El proyecto de ley de impuestos del Senado libera el gasto en monedas estables mientras que Bitcoin permanece en los formularios del IRS
Story summary
La propuesta circulada daría a las compras elegibles de monedas estables en dólares un tratamiento sin ganancias ni pérdidas sin un límite de valor establecido, mientras que el gasto ordinario de Bitcoin conservaría los informes de disposición. El proyecto de ley de impuestos posterior al Senado libera el gasto en monedas estables mientras Bitcoin permanece en los formularios del IRS apareció por primera vez en CryptoSla
📌 Key Highlights & Takeaways
- La propuesta circulada daría a las compras elegibles de monedas estables en dólares un tratamiento sin ganancias ni pérdidas sin un límite de valor establecido, mientras que el gasto ordinario de Bitcoin conservaría los informes de disposición.
- El proyecto de ley de impuestos posterior al Senado libera el gasto en monedas estables mientras Bitcoin permanece en los formularios del IRS apareció por primera vez en CryptoSla
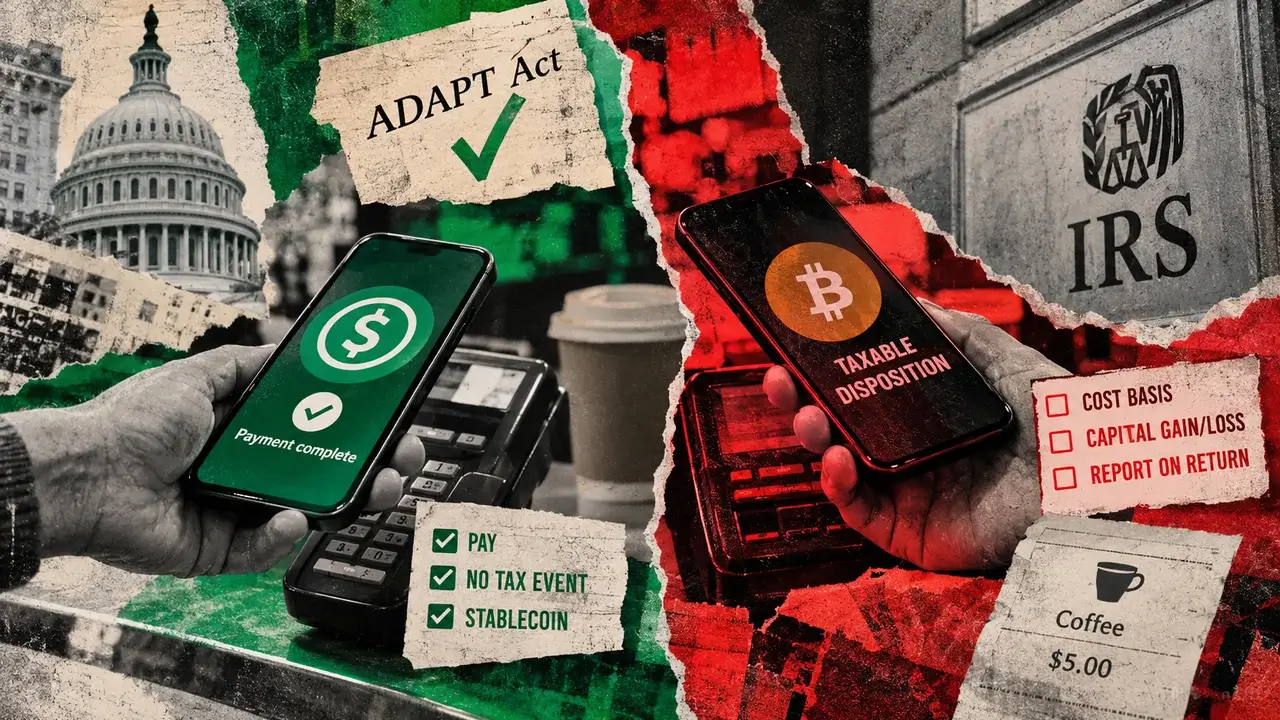
A coffee bought with a qualifying dollar stablecoin would avoid gain-or-loss recognition under the ADAPT Act that Sen. Steve Daines released Sept. 30. The same coffee bought with Bitcoin would still trigger the cost-basis calculation and capital gain or loss reporting that attach to spending digital assets.
Bloomberg Law reported Sept. 25 that Daines had circulated a draft and expected to introduce it the next week. The 56-page text released Sept. 30 carries the title Aligning Digital Assets with Principles of Taxation Act and lists Sens. Cynthia Lummis , Bernie Moreno and Tim Scott of South Carolina as cosponsors.
Under current IRS guidance, paying for goods or services with digital assets in any amount is a disposition. Holders of personal or investment assets must calculate and report capital gain or loss, which depends on the asset's value and cost basis.
A payment can produce a gain, a loss, or a break-even result, and the IRS uses a cup of coffee as its own example. A $5 Bitcoin purchase with an allocated basis of $3 produces a $2 capital gain that belongs on the return.
New section 1034 of the tax code would treat the disposition of covered payment stablecoins to buy products or services as a nonrecognition event. The relief covers gain or loss on the token itself, and sales taxes and other purchase obligations stay in place.
The token must be a qualified US dollar stablecoin, meaning one issued by a permitted payment stablecoin issuer under the GENIUS Act .
A foreign issuer qualifies through OCC registration or a Treasury finding that its home regime is comparable. It must appear in Treasury's most recent report before the payment, and the taxpayer must have acquired it at a price within 3% of $1.00.
Treasury would publish that report at least every three months, listing each qualified stablecoin actively traded within 3% of $1.00 during the 12 months ending the prior month. Users and payment companies would check the latest list when making a purchase.
Crypto Profit & Yield Calculator
Simulate trading returns, staking APY, and crypto gains with real-time fee modeling.
Source: CryptoSlate.
Read the full story at the original source ↗
For questions: mrsmithcons@gmail.com.
💎 On-Chain Wallet Tracking & Breakout Targets
Direct wallet address monitoring, smart money flows, and liquidity depth.
⚡ Track Whale Wallets Now ➔More from CryptoAce VIP
 🚀 RocketCoin Casino
Best Crypto Casinos 2026 – 5 Fastest Bitcoin Gambling Sites Ranked by Trust
Breaking coverage: Best Crypto Casinos 2026 – 5 Fastest Bitcoin Gambling Sites Ranked by Trust. Comprehensive ...
 ₿ Lucky Satoshi
El problema cuántico: Quantum no vendrá por su Bitcoin
Revista Bitcoin The Quantum Issue: Quantum no viene por su Bitcoin De The Quantum Issue: Brandon Black conside...
 ⚡ LiveCoin Bet
El cofundador de Zcash respalda Bitcoin protegido y dice que su objetivo de fin de año ZEC aún está en juego
El cofundador de Zcash, Eli Ben-Sasson, respalda a Shielded Bitcoin para transferencias privadas L1 y se manti...
 🪙 FreeFortune Crypto
Actualizaciones en vivo: Bitcoin logra pequeñas ganancias a medida que las acciones caen debido a la preocupación por la IA y el petróleo aumenta [Revisado por un analista senior].
La reunión de política monetaria de dos días de la Reserva Federal comienza mañana, y casi todos ahora esperan...