Why truly decentralized DeFi needs no legal exemption according to SEC Commissioner Hester Peirce
Story summary
SEC and CFTC actions focus on custody, access, routing, fees and intervention powers, each within a separate legal framework. The post Why truly decentralized DeFi needs no legal exemption according to SEC Commissioner Hester Peirce appeared first on CryptoSlate.
📌 Key Highlights & Takeaways
- SEC and CFTC actions focus on custody, access, routing, fees and intervention powers, each within a separate legal framework.
- The post Why truly decentralized DeFi needs no legal exemption according to SEC Commissioner Hester Peirce appeared first on CryptoSlate.
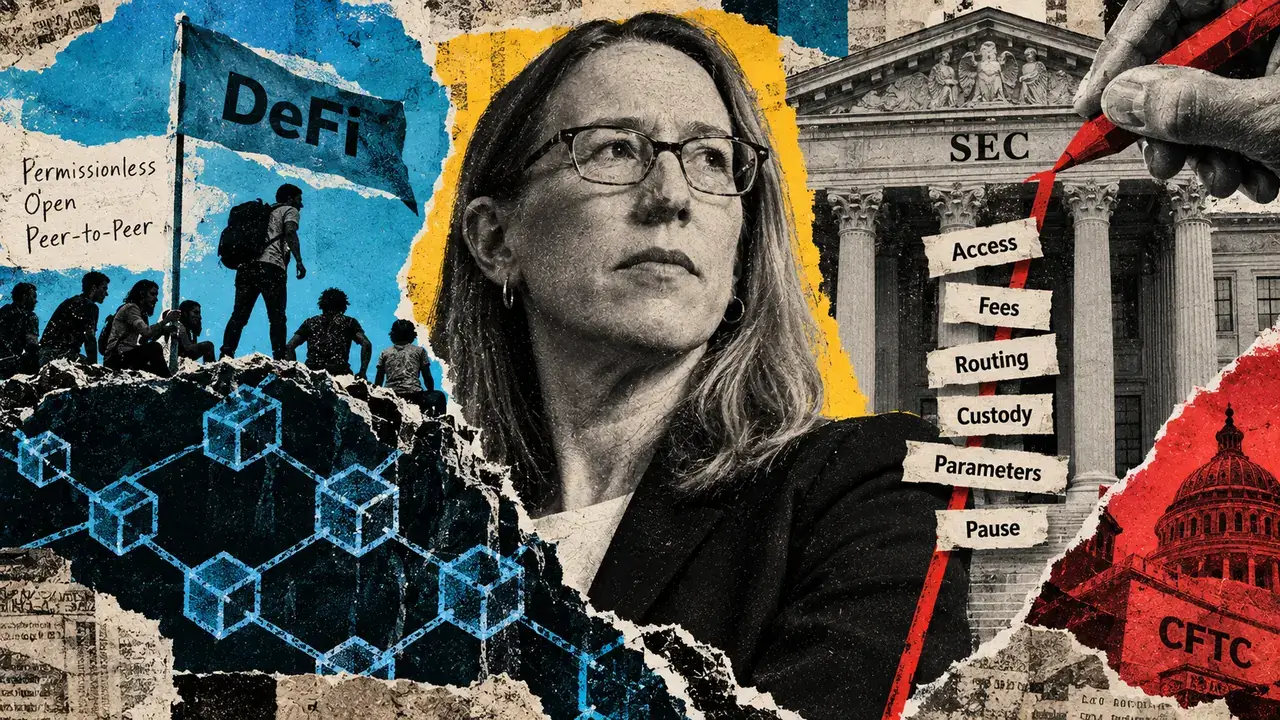
SEC Commissioner Hester Peirce drew a sharp line around decentralized finance on Sept. 17. She said investors need no exemption to use permissionless smart contracts for peer-to-peer trading. The SEC and CFTC actions examined here set separate limits on intermediary control.
The unresolved question is how much control a software provider can retain before it begins to resemble a regulated intermediary.
Peirce’s statement expressed her own position. A binding definition from the US Securities and Exchange Commission would require Commission action. The SEC’s tokenized-securities order and a separate staff statement leave her phrase “truly decentralized” undefined. Their specific provisions focus on custody, access, software parameters, fees, recommendations, routing and execution.
Each action operates under a different statute and carries a different legal effect. Together, they show how federal regulators are examining the authority that identifiable providers retain. A unified federal decentralization test remains absent.
The SEC’s Sept. 17 tokenized-securities order is an order of the Commission. It creates temporary, conditional relief for a defined Tokenized Securities Venue, or TSV, using automated market maker pools for permissioned trading in Tokenized NMS Stocks.
A TSV under the order performs two functions: It provides one or more AMM pools for permissioned participants, and it sets standards governing who may access those pools.
The order gives “provides” a functional meaning for that exemption. Selecting and designating a pool can count. Deploying its trading contract, changing its rules or parameters, setting its fees, or retaining authority to pause trading can also establish provision or control. Solely performing the administrative task of encoding a whitelist falls outside that definition.
Automation leaves several consequential choices in human hands. People may still choose the venue, set fees, pause activity or decide who gets in. Peirce placed the order outside decentralized finance and described genuinely permissionless software as a different model. The permissioned venue illustrates why operational powers matter even when smart contracts execute trades.
Crypto Profit & Yield Calculator
Simulate trading returns, staking APY, and crypto gains with real-time fee modeling.
Source: CryptoSlate.
On-Chain Whale Radar: Smart Money Cold Wallet Outflows & High-Yield DeFi Opportunities
Uncover high-yield crypto alpha, on-chain whale accumulation alerts, 100x altcoin gems, and automated DeFi yield opportunities before the retail crowd.
Track Whale Wallets ➔💎 On-Chain Wallet Tracking & Breakout Targets
Direct wallet address monitoring, smart money flows, and liquidity depth.
⚡ Track Whale Wallets Now ➔More from CryptoAce VIP
 🪙 FreeFortune Crypto
Top Crypto Staking Platforms With Highest APY in 2026
Breaking coverage: Top Crypto Staking Platforms With Highest APY in 2026. Comprehensive monitoring, ongoing st...
 🎮 GameVault 668
High-Definition Footage Of Pokémon Ruby And Sapphire On Official Pokémon Socials Sparks Nintendo Switch Port Speculation
The suspiciously HD Pokémon Ruby and Sapphire clip has fans convinced that Nintendo Switch ports of the games ...
 🚀 RocketCoin Casino
Best Bitcoin Casinos Ranked: Top 5 Highest-Paying Crypto Sites to Try in 2026
Breaking coverage reported by Sports Gambling Podcast: Best Bitcoin Casinos Ranked: Top 5 Highest-Paying Crypt...
Bitcoin Surges to Eight-Month High Above $85,000
Bitcoin has climbed above $85,000, reaching its highest level since January as the cryptocurrency market stage...