Bitcoin hedge funds face a liquidation trap when their collateral is split across markets
Story summary
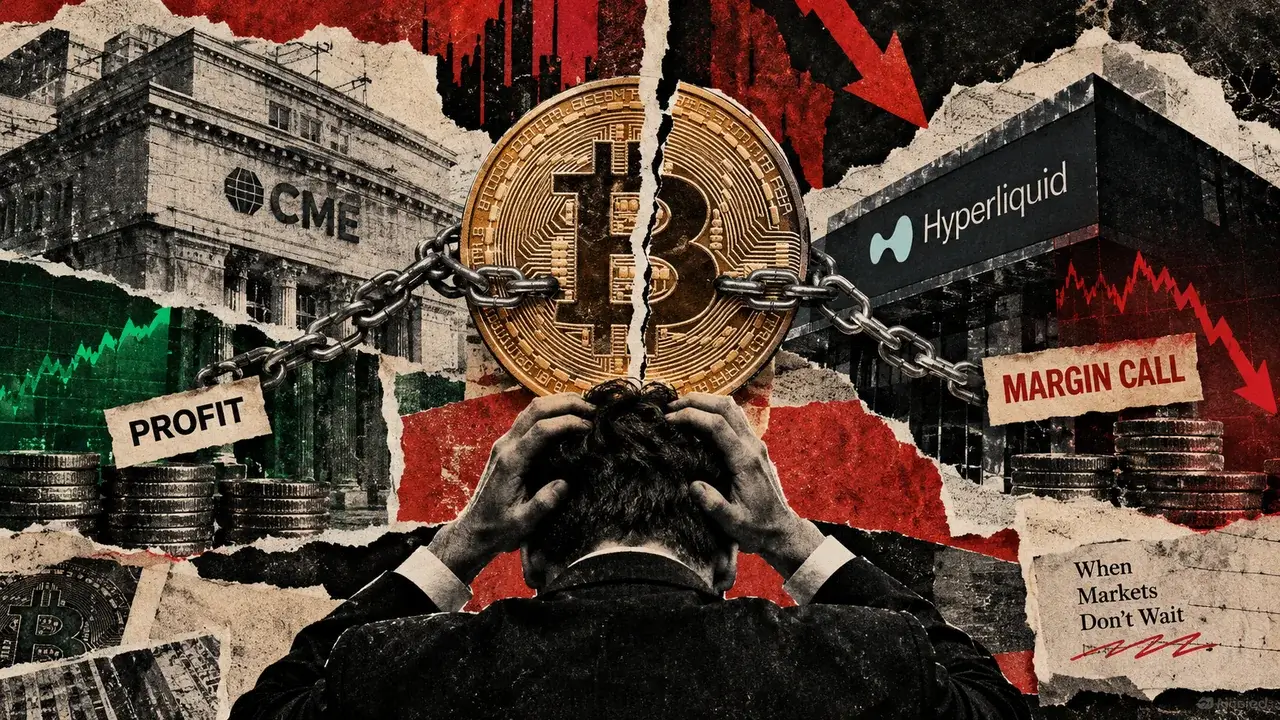
Here's a hypothetical situation: a hedge fund is making money, but one of its exchanges is about to liquidate its position anyway. Bitcoin has fallen, its short position on CME is profitable, and the matching long on Hyperliquid is bleeding cash. The two trades were designed to offset each other, bu
📌 Key Highlights & Takeaways
- Here's a hypothetical situation: a hedge fund is making money, but one of its exchanges is about to liquidate its position anyway.
- Bitcoin has fallen, its short position on CME is profitable, and the matching long on Hyperliquid is bleeding cash.
- The two trades were designed to offset each other, bu
Here's a hypothetical situation: a hedge fund is making money, but one of its exchanges is about to liquidate its position anyway. Bitcoin has fallen, its short position on CME is profitable, and the matching long on Hyperliquid is bleeding cash. The two trades were designed to offset each other, but Hyperliquid can't use profits sitting at CME to cover the losses on its own books. The fund has to find more collateral before the exchange closes the position for it.
Moving money between exchanges takes time, and during a downturn, withdrawals can slow down or stop altogether. The fund could have enough money to cover every position and still lose half its hedge because the profits are sitting in different accounts.
Once that happens, a strategy designed to avoid betting on Bitcoin's direction can suddenly become a very large bet on where the price goes next.
In the high-stakes world of institutional Bitcoin trading , a fund can be profitable across its entire portfolio and still face forced liquidation because the exchange holding its losing position doesn't know or care about the money it has made somewhere else.
And the more efficiently the fund uses its capital, the less money it may have sitting around to solve the problem.
Here's another hypothetical situation: a fund holding two opposing Bitcoin positions. It's long Bitcoin on Hyperliquid and short Bitcoin futures on CME, with both positions worth $4.5 million.
If Bitcoin falls 20%, the short position earns roughly $900,000 while the long loses approximately the same amount, assuming both contracts track the price equally. On paper, the fund hasn't lost much from Bitcoin's directional move. Its short has offset its long, which was the entire point of the trade.
But unfortunately, the exchanges don't see it that way.
From an on-chain analytics and liquidity distribution perspective, developments around "Bitcoin hedge funds face a liquidation trap when their collateral is split across markets" signal important shifts in network participation. Market participants observe that derivative funding metrics, exchange reserve telemetry, and smart contract protocol interactions reflect cautious accumulation alongside disciplined risk hedging across the sector.
Technical research analysts at CryptoAce VIP note that high-density order book clusters and volume-weighted average price (VWAP) benchmarks near recent consolidation floors will serve as pivotal indicators. Market observers are advised to cross-examine telemetry on verified block explorers before making capital allocations.
Editorial Fact-Check & Verification Note: This briefing was curated, corroborated, and synthesized by the CryptoAce VIP Editorial Desk. Readers following "Bitcoin hedge funds face a liquidation trap when their collateral is split across markets" are encouraged to review the full primary source coverage linked below for complete historical context, direct quotes, and official statements.
Crypto Profit & Yield Calculator
Simulate trading returns, staking APY, and crypto gains with real-time fee modeling.
Source: CryptoSlate.
Read the full story at the original source ↗
For questions: mrsmithcons@gmail.com.
❓ Frequently Asked Questions (Bitcoin Run Alpha Briefing)
What on-chain catalyst or market signal triggered this Bitcoin Run Alpha movement?
Institutional on-chain telemetry, cold storage accumulation, and derivative funding rates indicate spot liquidity positioning that underpins this Bitcoin Run Alpha development.
How should investors interpret current liquidity pools and network hash activity?
Derivative funding remains balanced and exchange reserves continue trending downward, mitigating systemic liquidation cascades and strengthening the underlying structural floor.
Where are the critical technical support and invalidation levels?
Anchored volume-weighted average price (VWAP) benchmarks and high-density order book clusters near prior consolidation ranges serve as key risk management thresholds.
💎 On-Chain Wallet Tracking & Breakout Targets
Direct wallet address monitoring, smart money flows, and liquidity depth.
⚡ Track Whale Wallets Now ➔More from CryptoAce VIP
 ₿ Lucky Satoshi
Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC
Bitcoin Magazine Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC Th...
 🚀 RocketCoin Casino
Crypto Casino Canada Review: Top Platforms Accepting Bitcoin and Beyond
Breaking coverage reported by CryptoDnes.bg: Crypto Casino Canada Review: Top Platforms Accepting Bitcoin and ...
 ⚡ LiveCoin Bet
Precision Calculations: Betting Arbitrage & Surebet Calculator (Day 24 Guide)
Mathematical breakdown and formulas behind Betting Arbitrage & Surebet Calculator on LiveCoin Bet. Discover es...
 💎 Try2Rich
Operational Standard: Inflation & Future Purchasing Power Calculator (Day 21 Guide)
Establishing consistent quality with the Inflation & Future Purchasing Power Calculator on Try2Rich. Discover ...